
📋 Table of Contents
- What Is a Budget, Really? (A Definition Your Kid Actually Gets)
- Why Budgeting Skills Matter More Than Math Grades
- The Mistakes Parents Make When Teaching Budgets
- What Actually Works: The 3-Jar Budget System
- Age-by-Age: How to Explain Budgets at Every Stage
- What Parents Are Actually Asking
- Frequently Asked Questions
My 9-year-old asked me last month: "Mom, what's a budget?" I opened my mouth to explain and realized I didn't have a simple answer. Not one a kid would actually understand. I knew what a budget was for me — spreadsheets, categories, that sinking feeling when I overspent on coffee. But for her? I needed something cleaner.
A budget for kids is not a spreadsheet. It's a plan for your money before you spend it. And here's the part most parents miss: your kid is already budgeting, whether they know the word or not. When they decide to save allowance for a video game instead of buying candy, that's a budget. When they split birthday money between "spend now" and "save later," that's a budget. The job isn't to teach them something new. It's to give them a name for what they're already doing — and a system that makes it easier.
🌱 Free Download
My First Money Kit
The 3-Jar System printable + spend/save/give labels — free, instant download, works for all ages
Get the Free Kit →What Is a Budget, Really? (A Definition Your Kid Actually Gets)
When adults say "budget," we usually mean a spreadsheet with 47 categories and color-coded cells. For a kid, that's useless. A budget is simply this: a plan for your money before you spend it.
Here's how I explained it to my daughter. I held up a $10 bill and said, "You have ten dollars. You want a $7 book and a $4 toy. You can't buy both. A budget is the plan you make before you walk into the store." She got it immediately. Not because she's a genius — because it's concrete.
The power of a budget for kids is that it turns abstract numbers into visible choices. When your kid sees $10 split into three jars — Save, Spend, Give — they can literally see where their money is going. They don't need to understand percentages or compound interest yet. They need to understand that money is finite, and that choosing one thing means not choosing another.
According to the Consumer Financial Protection Bureau (CFPB), children who learn basic money management skills before age 12 are more likely to save regularly, avoid high-cost borrowing, and maintain healthy credit as adults. The budget is the foundation. Everything else — saving, investing, giving — sits on top of it.
Why Budgeting Skills Matter More Than Math Grades
I spent a decade teaching middle school math. I can tell you with absolute certainty that the kids who struggled with algebra but understood how to manage $20 were better prepared for adulthood than the kids who aced every test but couldn't make a spending decision.
Here's the data: the Next Gen Personal Finance (NGPF) found that only 19% of Gen Z can answer basic money questions correctly. Not advanced investing questions — basic ones like "what happens to your money in a savings account?" That's not a math problem. That's a budgeting problem. It's the gap between knowing numbers and knowing what to do with them.
A budget teaches something no worksheet can: trade-offs. When your kid has $10 and wants two things that cost $8 each, they have to choose. That choice — that small, low-stakes moment of deciding — is where financial literacy actually happens. Not in a classroom. Not on a test. In the kitchen, staring at three jars and deciding where the next dollar goes.
My son opened his first budget at 11. Within a month, he stopped asking me to buy him random things at the store. Not because I said no — because he had his own money, his own plan, and his own priorities. That shift from "ask Mom" to "check my budget" is the entire point.
The Mistakes Parents Make When Teaching Budgets
I've talked to hundreds of parents about money, and I see the same mistakes over and over. I made most of them myself.
Mistake 1: Making It Too Complicated
Your kid does not need 20 budget categories. They need three: Save, Spend, Give. When parents introduce spreadsheets and percentages too early, kids tune out. A budget should feel like a game, not homework. Start with jars. Add complexity only when they ask for it.
Mistake 2: Only Talking About Restrictions
If your budget conversations sound like "no, we can't afford that," your kid will learn to associate budgeting with deprivation. A budget is not a list of things you can't buy. It's a plan for the things you can. Frame it positively: "Your budget says you have $5 for spending this week. What do you want to spend it on?"
Mistake 3: Not Modeling It Yourself
Kids watch everything. If you never talk about your own budget — even in simple terms — they won't see budgeting as something real adults do. You don't need to share your salary. Just say things like, "I'm putting money in our vacation jar this month," or "My grocery budget is $150 this week." Make it visible.
Mistake 4: Using Fake Money
Play money and classroom simulations have their place, but a budget only works with real dollars your kid actually controls. If the consequences of a bad decision are imaginary, the learning is imaginary too. Start with real allowance, real birthday money, real earnings from chores or side hustles. Check out our guide to how kids can make money for real earning ideas.
Mistake 5: Waiting Until They're "Old Enough"
By the time most parents think their kid is "old enough" for a budget, that kid has already formed spending habits — usually the habit of spending whatever is in front of them. I started my daughter at 7. My son at 11. Both learned, but my daughter's habits are deeper because she started earlier. There is no minimum age for a jar and a conversation.
Ages 5–8
Money Seeds
The complete earn-save-give workbook for young kids. 30 pages of activities, trackers, and real-world money lessons that make budgeting click.
Get Money Seeds ($17) →What Actually Works: The 3-Jar Budget System
After years of trial and error with my own kids and feedback from hundreds of parents, the 3-jar system is still the best starting point. It's visual, it's simple, and it works for every age with minor tweaks.
Here's the full setup:
Step 1: Get Three Clear Jars
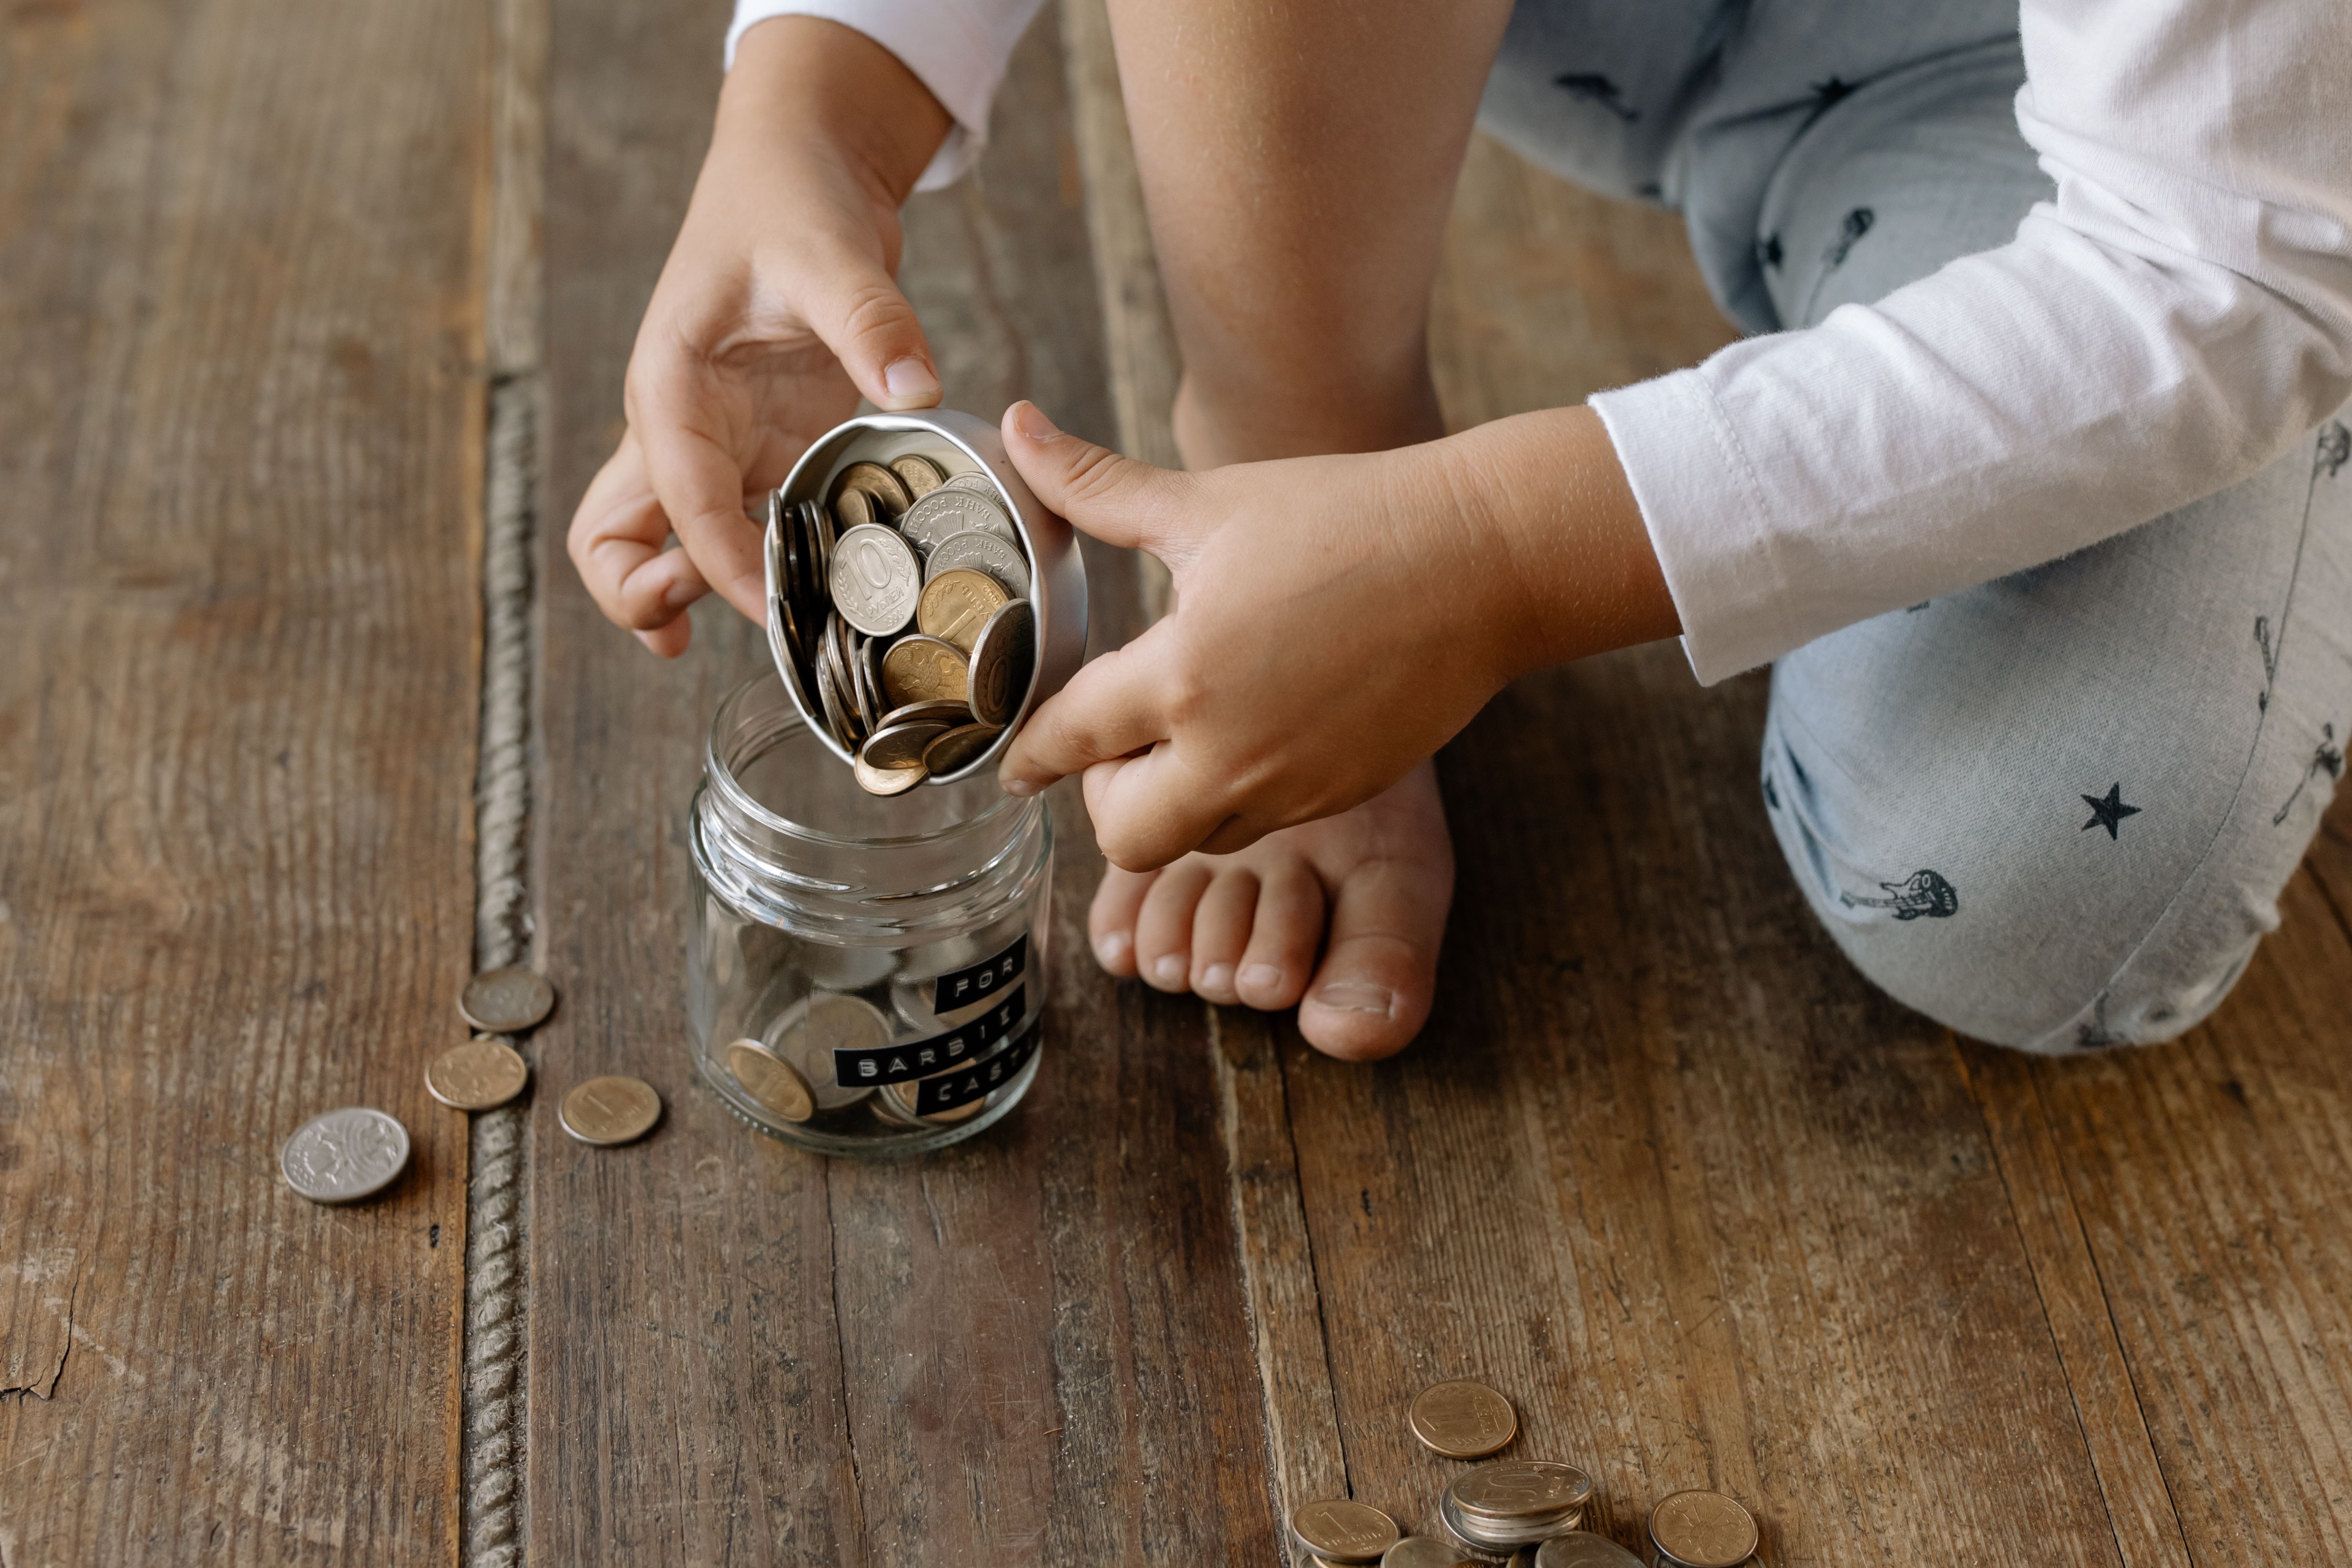
Clear is important. Your kid needs to see the money growing or shrinking. Mason jars work great. So do clear plastic containers. Label them: Save, Spend, and Give. We have free printable labels in our My First Money Kit.
Step 2: Decide the Split Together
For younger kids, keep it simple: half in Spend, half in Save, with a small amount for Give. For older kids, try the 50/40/10 rule: 50% Spend, 40% Save, 10% Give. The key is deciding together. If you dictate the split, it's your budget. If they choose it, it's theirs.
Step 3: Fund the Jars With Real Money
Allowance is the easiest source, but it doesn't have to be the only one. Birthday money, chore earnings, side hustle income — it all goes into the jars. The important thing is that the money is theirs to manage. For more on setting up allowance, see our allowance system guide.
Step 4: Set a Savings Goal
A jar labeled "Save" with no purpose is just a smaller spending jar waiting to be emptied. Help your kid pick a specific goal: a $30 LEGO set, a new book, a donation to the animal shelter. Write the goal on the jar. Every deposit becomes visible progress. Our savings goal tracker pairs perfectly with this system.
Step 5: Review Weekly
Pick a day — Sunday night works for us — and review the jars together. How much is in each? What did they spend this week? What do they wish they hadn't bought? This is not a lecture. It's a conversation. The goal is awareness, not shame.
According to Investopedia, the 50/30/20 rule is the adult equivalent of this system: 50% needs, 30% wants, 20% savings. Your kid's 3-jar budget is training wheels for that framework. When they hit adulthood, the habit is already there.
Age-by-Age: How to Explain Budgets at Every Stage
Kids are not mini adults. Their brains are developing the ability to think about future consequences at different rates. Here's how to match the budget to their stage:
Ages 5–7: The Visual Phase
At this age, money is still abstract. A budget needs to be something they can see and touch. Use the 3-jar system with physical coins and bills. Don't worry about percentages. Just say, "Some for now, some for later, some to share." Let them move the money themselves. The act of dropping a quarter in the Save jar is the lesson.
Start with our 3-jar system for kids guide, which has printable labels and a step-by-step setup for this age group.
Ages 8–11: The Goal Phase
Kids this age can handle simple percentages and longer time horizons. Introduce the idea that Save isn't just "not spending" — it's "spending later on something bigger." Help them calculate how many weeks of $5 allowance it takes to buy a $40 item. That simple math — 40 divided by 5 — is more powerful than any lecture about delayed gratification.
My 11-year-old is currently saving for a $60 gaming accessory. He gets $8 per week. He figured out it will take 8 weeks. He also figured out that if he does extra chores for $3 each, he can cut that to 5 weeks. That's budgeting. That's math he cares about.
Ages 12–14: The Independence Phase
Middle schoolers want autonomy. Give it to them — within boundaries. Transfer their budget to a digital app or a simple spreadsheet. Add a fourth category if they want: "Invest." Even $5 per month into a custodial account teaches the habit. At this age, they should also be earning some of their own money. Our how to make money as a kid guide has age-appropriate ideas.
Ages 15–18: The Real World Phase
By high school, a budget should look like a real budget. Income (allowance + job), fixed expenses (phone bill, gas, subscriptions), savings goals, and discretionary spending. They should know what a savings rate is and why 20% is a good target. They should understand that a budget is not a restriction — it's a plan for freedom.
According to the Next Gen Personal Finance (NGPF), teens who practice budgeting with real income develop significantly stronger financial confidence than those who only learn from textbooks. The real world is the best classroom.
What Parents Are Actually Asking
I spend a lot of time reading what parents are genuinely confused about. Here's what's coming up again and again:
"I want to teach my 8-year-old about budgeting but I don't want to make it boring or feel like a punishment. Has anyone found a system that actually works?"
Yes — and the answer is simpler than you think. The 3-jar system works because it's visual, it's hands-on, and it gives your kid control. The key is to let them make the split decision, even if you think they're choosing wrong. My daughter once put 80% in Spend and 10% in Save. She ran out of spending money in four days and watched her Save jar sit empty. The next week, she adjusted to 50/40/10 without me saying a word. Experience is the teacher.
"Should I tie my kid's allowance to chores or just give it to them? I want them to learn budgeting but I also don't want to pay them for basic responsibilities like making their bed."
This is the great parenting debate, and I've tried both ways. Here's what worked for us: base allowance is not tied to chores — it's a tool for learning budgeting. Extra money can be earned through extra chores. This separates "family responsibility" from "earning opportunity." Your kid gets consistent practice with budgeting, plus the option to earn more if they want to reach a goal faster. For our full setup, see how to set up an allowance system for kids.
"My teenager thinks budgeting is just about not having fun. How do I change that mindset?"
Reframe the language. Don't say "we can't afford that." Say "that's not in the budget this month, but we can put it in next month's plan." A budget is not a wall — it's a door. It tells you what you CAN do, not just what you can't. When my son wanted a $90 headset, we put it in his budget. It took six weeks. When he finally bought it, he appreciated it more than anything I'd ever impulse-bought him.
Frequently Asked Questions
What is a budget for kids?
A budget for kids is a simple plan for how they will use their money before they spend it. For young children, this usually means dividing money into categories like save, spend, and give using clear jars or envelopes. The goal is to teach them that money is finite and that choices about spending have trade-offs.
At what age should kids start learning about budgets?
Kids can start learning budget concepts as early as age 5, using visual tools like the 3-jar system. By ages 8–11, they can handle simple percentages and savings goals. Teenagers should be managing a real budget with their own income from allowance or jobs. The earlier they start, the more natural the habit becomes.
How do you explain a budget to a 5-year-old?
Use concrete, visual language. A budget for a 5-year-old is simply "a plan for your money." Show them three jars labeled Save, Spend, and Give. When they get a dollar, they choose how much goes in each jar. Keep it simple — no percentages, no spreadsheets, just the idea that money gets split into different buckets for different purposes.
What percentage should kids save vs. spend?
A simple rule for kids is the 50/40/10 split: 50% for spending, 40% for saving, and 10% for giving. For younger kids, you can simplify this to roughly half for spending and half for saving, with a small portion for charity. The exact numbers matter less than building the habit of splitting money intentionally.
Should kids budget their allowance or just save it?
Kids should do both. Budgeting means deciding in advance how to split allowance between spending, saving, and giving — not just stashing it all in a piggy bank. If they only save, they never learn to make spending decisions. If they only spend, they never learn delayed gratification. A budget gives them practice with both.
How is a kids' budget different from an adult budget?
A kids' budget is much simpler. Adults track dozens of categories — rent, groceries, insurance, retirement. A child's budget typically has just three categories: save, spend, and give. The goal isn't to replicate adult complexity; it's to teach the underlying principle that money is finite and that planning ahead leads to better outcomes.
Before You Go
Start With the Free Money Kit
Download the 3-Jar System printable, spend/save/give labels, and a simple budget tracker your kid can use today — no email required.
Get It Free →This article may contain affiliate links. WealthSprout earns a small commission if you purchase through our links, at no extra cost to you. We only recommend products we believe in. Nothing in this article constitutes financial advice — see our Financial Disclaimer.