📋 Table of Contents
What Eight-Year-Olds Are Ready For
Your 8-year-old is in a sweet spot. They can add and subtract without counting on fingers (usually), they understand that waiting three weeks is different from waiting three days, and—this is the big one—they're starting to grasp cause and effect over time.
This is the age where money stops being just "those round things" and starts being a tool. They can connect the dots: if I save my allowance for four weeks instead of spending it on Friday, I can buy that bigger thing I actually want.
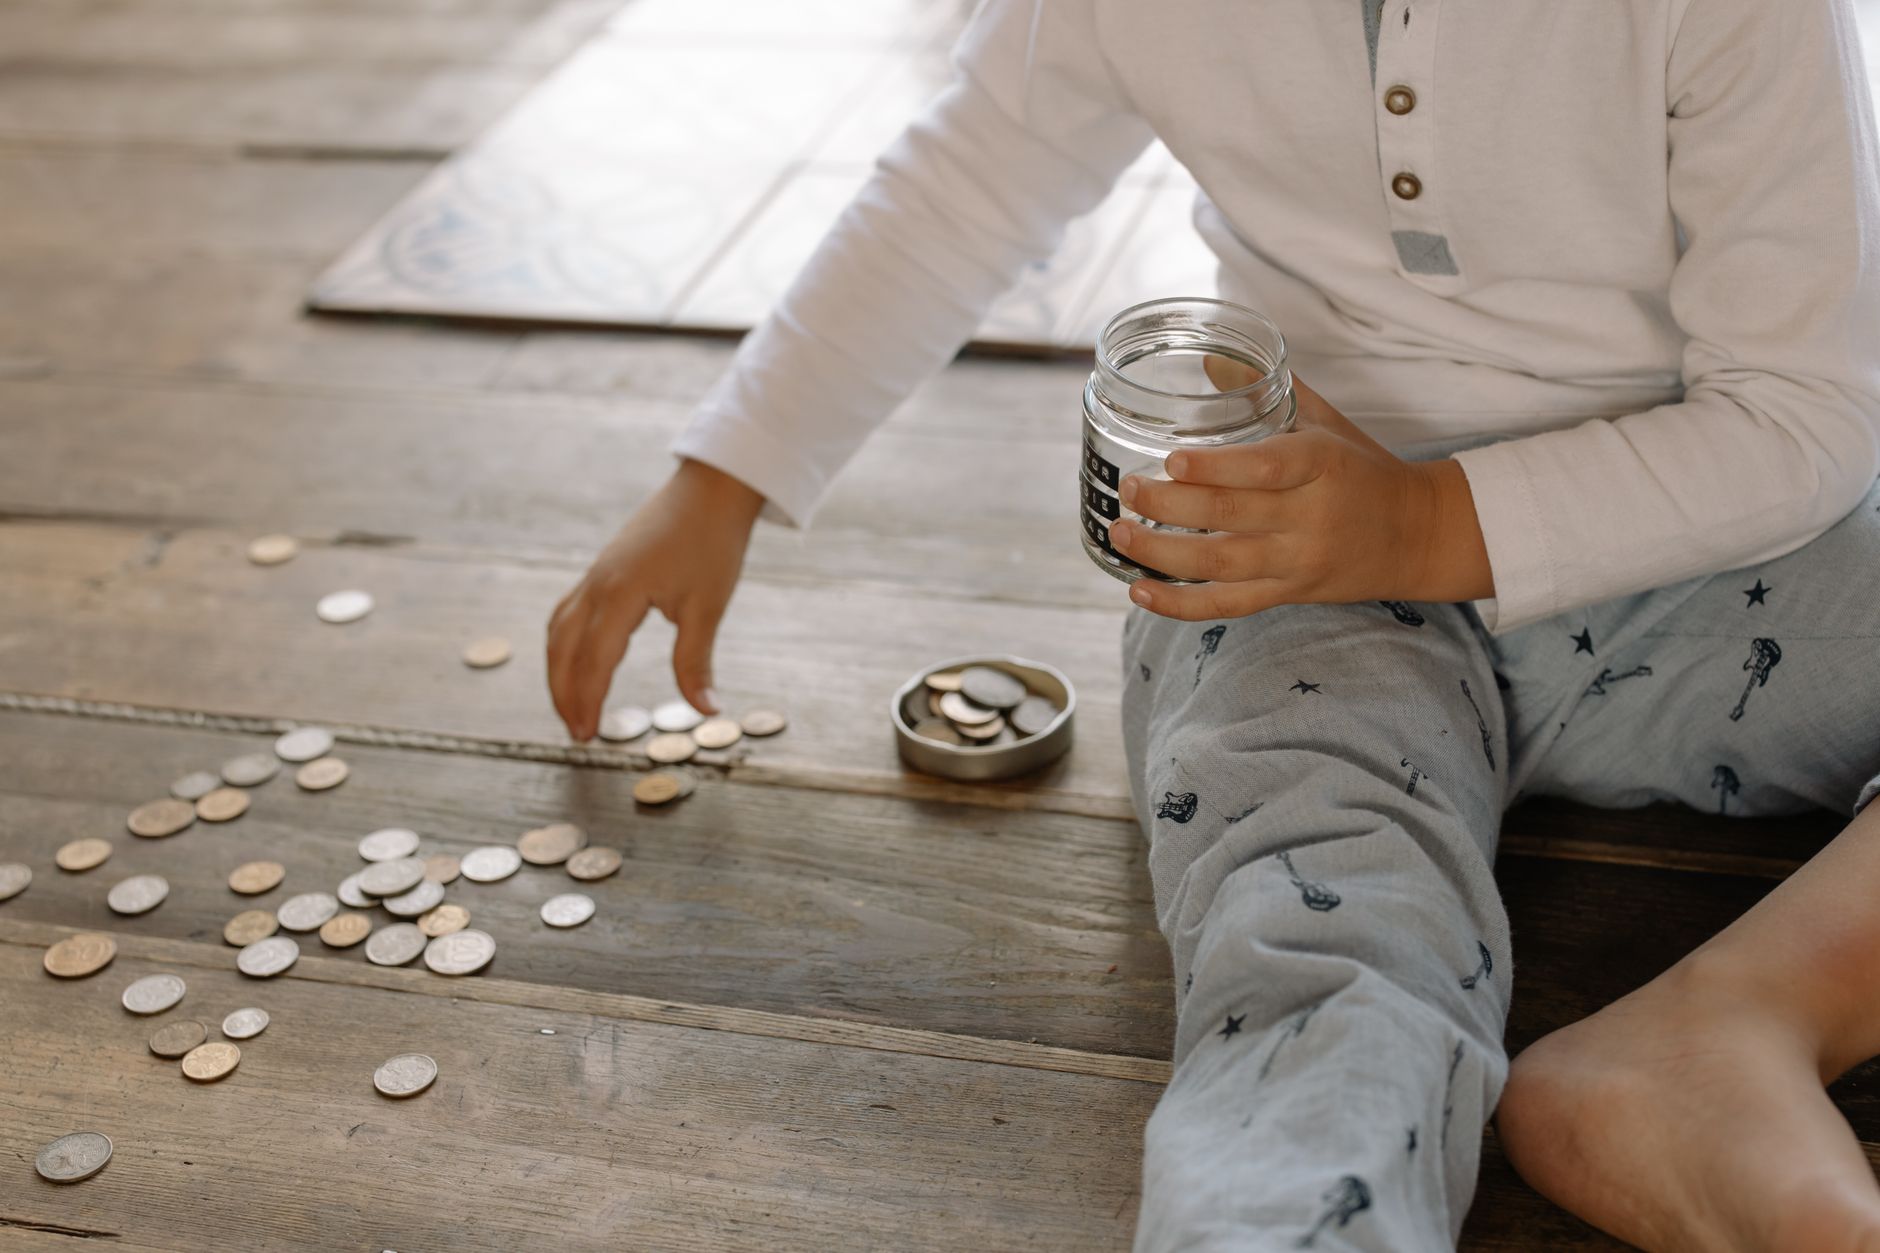
Eight-year-olds are also concrete thinkers. Abstract concepts like "your money is growing" don't land. But watching a jar fill up? That clicks immediately. Their brains are wired to understand what they can see, which is exactly why the container you choose for their money actually matters more than most parents realize.
Developmentally, this is when kids can:
- Handle simple multi-step goals ("Save $20 for the Lego set")
- Wait 3-4 weeks for something they want
- Understand that more coins doesn't always mean more money (five quarters vs. twenty nickels)
- Make basic spending decisions and learn from mild buyer's remorse
- Track progress visually better than numerically
If your kid is asking how much they have every single day, or getting frustrated they can't "see" their money adding up, that's not impatience—that's their brain doing exactly what it should at this age.
What They're Ready to Learn About Money
At eight, your kid is ready for the fundamental money concept that will serve them for life: delayed gratification has a visible reward.
Not the phrase "delayed gratification"—that's adult-speak. But the experience of watching their money pile up, seeing it get closer to a goal, and then actually buying the thing they wanted? That's the neural pathway that makes saving feel good instead of punishing.
Here's what else 8-year-olds can handle:
Visual progress tracking. They need to see their money growing. Telling them "you have $8.47 now" is information. Showing them a jar that's half-full is motivation.
Simple categorization. This is the perfect age for the 3-jar system—spend, save, share. They can understand that money can have different jobs, especially if those jobs have different physical spaces.
Earning and saving cycles. If your kid is getting an allowance or earning money through simple jobs, they can start to see the pattern: earn, save, reach goal, buy thing, start over. The container you use either supports this cycle or hides it.
Making trade-off decisions. Should I buy this $5 toy now or wait two more weeks for the $15 one? Eight-year-olds can think through these choices if they can see how much they have and how much more they need.
According to research from the Next Gen Personal Finance (NGPF), kids who have tangible, visible money experiences between ages 5-10 develop better saving habits than those who only interact with abstract accounts or apps.
How to Start the Conversation
Don't overthink this. You're not teaching Economics 101—you're setting up a container. But how you introduce it shapes whether your kid sees saving as exciting or boring.
Script if they currently have a piggy bank:
"Hey, I've been thinking. You're getting really good at saving for [specific thing they want]. Want to try something that makes it easier to see how close you're getting? We could use a clear jar so you can actually watch your money pile up."
Script if they're brand new to saving:
"You know how you really want [that specific $20 thing]? Let's set up a special jar just for that. Every time you add money, you'll be able to see it getting closer to the top. When it's full, you'll have enough."
Script if they have money scattered everywhere (parents, this is so common):
"Let's do a money roundup. Grab all the coins and dollars from your room and we'll count it together. Then you can decide—do you want to save it for something big, or spend some now and save some?"
The key is tying the container to their goal, not your lesson plan. You're not saying "we're going to learn about saving." You're saying "here's a tool that helps you get the thing you want."
Let them help choose the jar or bank. If your kid picks out a jar at the dollar store themselves, they're already more invested. Literally—they're investing attention and ownership.
The Real Comparison: Piggy Bank vs. Clear Jar
Okay, here's what actually matters. Both containers hold money. But they teach completely different lessons.
The Case for Clear Jars
Pros:
- Instant visual feedback. Your kid adds a dollar, they see the pile grow. This is neurological gold for 8-year-olds. The reward center in their brain lights up before they even reach the goal.
- Built-in progress tracker. No need to ask "how much do I have?"—they can see it. You can even mark a goal line with a rubber band or tape.
- Reduces the need to break it open. With a piggy bank, there's mystery and temptation. With a jar, they can see exactly what they have, which weirdly makes them less likely to dump it out constantly.
- Teaches volume and space. They start to understand that a jar half-full of quarters is worth more than a jar full of pennies. That's pre-algebra thinking.
- Easy access for counting practice. Unscrew the lid, count together, put it back. No breaking, no sawing, no forcing coins through tiny slots.
- Cheap and easy to find. Mason jars, pasta sauce jars, old peanut butter containers. You probably have three in your recycling right now.
Cons:
- Too easy to access. Some kids will unscrew that lid daily. If your kid has zero impulse control yet, a jar might enable too much dipping into savings.
- Not as "special." A jar is utilitarian. It doesn't have the sentimental charm of a ceramic puppy bank from Grandma.
- Can break. Glass jars and tile floors are natural enemies. Plastic is safer for younger kids.
The Case for Piggy Banks
Pros:
- Creates a mental barrier. That slot is one-way. Money goes in, and getting it out requires effort. For some kids, this friction is exactly what they need to avoid impulsive spending.
- Feels official and special. There's something about a "real" piggy bank that makes saving feel like a bigger deal. It's ceremonial.
- Teaches commitment. Once money goes in, it's committed. This can be powerful for kids who need help with "out of sight, out of mind."
- Gift-friendly. Let's be honest, a ceramic elephant bank is a better birthday gift from Grandma than a jar that held pickles.
Cons:
- Zero visibility. Your kid has no idea if they have $3 or $13 in there. This can be demotivating for 8-year-olds who need to see progress.
- Requires breaking or frustrating removal. Most piggy banks either have a plug on the bottom (which your kid can't open without dumping everything) or need to be broken. The breaking part is fun once. It's not a sustainable system.
- Harder to count and learn from. If they can't easily access the money, you can't do regular counting practice together.
- Becomes "magic money." Without visibility, the bank becomes a black box. Money goes in, and... then what? The cause-and-effect link gets fuzzy.
What the Research Says
The Consumer Financial Protection Bureau (CFPB) recommends visual, hands-on tools for kids under 10. Their research shows that children learn money concepts faster when they can physically manipulate and see their money rather than relying on abstract tracking.
Translation: for 8-year-olds specifically, clear beats opaque.
Maya's Take: When to Use What
Here's my honest opinion after trying both with my own kids and hearing from hundreds of WealthSprout parents:
Use a clear jar if:
- Your kid is saving for a specific, short-term goal (2-8 weeks out)
- They get discouraged easily and need visible progress
- You want to do regular counting and math practice together
- They're learning the 3-jar system (spend/save/share)
Use a piggy bank if:
- Your kid struggles with impulse control and needs that physical barrier
- They're saving for a long-term goal (6+ months) and checking daily would be demotivating
- They specifically love their piggy bank and are already motivated by it
Use both if:
- You want short-term savings visible (clear jar) and long-term savings protected (piggy bank)
- Your kid is ready to manage multiple categories of money
There's no wrong answer here. The best container is the one your kid actually uses and feels excited about.
What Parents Are Getting Wrong
Mistake #1: Choosing based on what looks cute in their room
I get it. That ceramic dinosaur bank matches the bedding. But if your kid never interacts with it because they can't see their progress, it's just decor. Function over Pinterest-ability for this one.
Mistake #2: Making it too hard to access for counting
Some parents are so worried about kids "raiding" their savings that they make it impossible to even count the money together. If you have to use a butter knife to pry open the rubber stopper every time, you won't do regular counting practice—and that practice is where the learning happens.
Mistake #3: Not connecting the container to a specific goal
A jar or bank sitting there collecting random money doesn't teach much. But a jar with a goal tracker taped to it—"Saving for the $25 art set!"—transforms it from a container into a visual commitment device.
Mistake #4: Switching containers mid-goal
If your kid is halfway to their goal with a piggy bank, don't suddenly switch to a jar because you read this article. Let them finish this goal, then suggest trying something new for the next one. Changing systems mid-stream is confusing and demotivating.
Mistake #5: Forgetting that the container is just the start
Neither a jar nor a bank will magically teach your kid about money. The learning happens in the conversations you have while using it. "You added three dollars today! How much more until you hit your goal?" That's the teaching moment—not the container itself.
Reddit & Quora: What Parents Are Asking
I came across this question on Quora: "What are some creative ways to store a lot of loose change apart from the traditional piggy bank?"
Here's what I wish I could tell every parent who's googling this: the question isn't really about storage. It's about visibility and motivation.
For 8-year-olds, "creative" doesn't matter. Functional does. A clear jar isn't fancy, but it works because your kid can see their progress. That visibility is the entire game at this age.
If you want to get creative, try this: use a clear jar but let your kid decorate a paper wrapper that goes around it with their goal written in huge letters. Or use a clear jar inside a larger clear container, so they can see both the money and how close they're getting to filling the outer container. Or stack multiple clear jars—one for spend, one for save, one for share.
The creativity should enhance visibility, not hide it. At eight, your kid's brain rewards what it can see accumulating. Give them that visual win.
Tools & Resources to Use Alongside the Jar or Bank
The container holds the money. These tools make the learning stick:
Goal tracker sheet. Print or draw a simple chart showing how much your kid needs and how much they have. Update it together every time they add money. Our free goal tracker printable works great taped right next to the jar.
Coin counting mat. A placemat or piece of paper with circles drawn for quarters, dimes, nickels, and pennies. Dump the jar, sort the coins, count together. This is math practice that doesn't feel like homework.
Allowance tracker. If your kid earns regular allowance, a simple calendar where they mark each payment helps them see the earning and the saving pattern. I didn't understand this until I was 34—helping your kid see both sides of the money flow is huge.
A "spend" and "save" system. Even if you're using a clear jar for savings, your kid needs somewhere for spending money too. Two jars, two banks, or one of each—just make it clear which money is for goals and which is for right-now wants. The 3-jar system adds a "share" category, which is perfect if your kid is ready for that level of complexity.
Real-life examples. Point out saving in action when you see it. "See how the barista has a tip jar where you can see the money? That's because people tip more when they can see it filling up. Same reason your clear jar works for you."
According to Investopedia's guide on teaching kids financial responsibility, tangible tools paired with consistent conversations create lasting money habits far better than either one alone.
Frequently Asked Questions
Should I let my 8-year-old keep all their money in one place or split it up?
Split it up, but keep it simple. At eight, they can handle two or three categories max: spend money (for short-term wants) and save money (for bigger goals). If your kid is interested, add a third for sharing/giving. More than three categories and it becomes administrative work instead of learning.
Use different containers for each so the categories stay physically separate. Three clear jars labeled with tape works perfectly.
What if my kid wants to use a piggy bank that you can't see through?
Let them. Seriously. If they're genuinely excited about that ceramic unicorn bank, the motivation from loving the bank outweighs the visibility benefit of a jar. You can still do regular counting sessions—just schedule them weekly and make it a thing you do together.
That said, if they start getting frustrated or losing interest, you can gently suggest trying a clear jar "just for this next goal" and see if they like it better.
How much money should an 8-year-old be saving?
There's no magic number. What matters is that they're experiencing the save-and-reach-goal cycle regularly enough to build the habit. If they're getting $5/week in allowance, maybe they save $2-3 of it. If they only get money occasionally, even saving $1 at a time works.
The goal isn't the amount—it's the pattern. Money comes in, some goes to savings, savings grows, goal is reached, repeat.
Can my kid use a clear jar for long-term saving, or is that only for short-term goals?
You can, but it's trickier. For goals longer than 2-3 months, eight-year-olds often lose steam. The jar fills so slowly that the visual progress isn't motivating anymore—it's just a reminder of how far they still have to go.
If your kid is saving long-term, consider using a piggy bank they only open quarterly, or splitting their savings: short-term goals in a clear jar, long-term in a bank or even a savings account they can't access daily.
What's the best size jar to use?
Match the jar size to the goal size. Saving $20? A standard mason jar is perfect. Saving $100? You'll want something bigger, or the jar will fill up before they hit their goal (which is confusing).
Here's a trick: estimate how much physical space their goal amount will take in coins and bills, then pick a jar that will be 3/4 full when they reach it. You want them to see it filling up, but not overflowing.
From WealthSprout
Start Your Kid's Money Journey Today
Our Money Seeds program is built for ages 5–8 — the exact age group where the jar habit starts. Workbooks, goal trackers, and conversation starters that make money fun.
Explore Money Seeds →This article may contain affiliate links. WealthSprout earns a small commission if you purchase through our links, at no extra cost to you. We only recommend products we believe in. Nothing in this article constitutes financial advice — see our Financial Disclaimer.